IBC Section 7 Financial Creditor Petition Lawyer in Delhi
Global Vision Law Firm files and defends Section 7 IBC applications before the NCLT in Delhi: Form 1 petitions, proof of default, admission hearings, CIRP and Committee of Creditors representation, and NCLAT appeals. Led by Advocate Amarendra Kumar Dubey with 13+ years of experience and 1400+ cases handled and successfully executed, we act for banks, NBFCs, lenders, home buyers, guarantors and corporate debtors.
- What is Section 7
- Who can file
- Default & threshold
- Documents
- Process & timeline
- Section 7 vs 9 vs 10
- Defences
- Key judgments
- After admission
- FAQ
What Is a Section 7 Petition Under the IBC?
Short answer
Section 7 of the Insolvency and Bankruptcy Code, 2016 lets a financial creditor apply to the NCLT to start the Corporate Insolvency Resolution Process (CIRP) against a corporate debtor that has defaulted on a financial debt of Rs 1 crore or more. The application is made in Form 1 with evidence of the debt and the default.
A Section 7 petition is the main route for lenders to push a defaulting company into a time-bound insolvency process. If the NCLT is satisfied that a default has occurred, the application is complete and no disciplinary proceedings are pending against the proposed resolution professional, it admits the petition, and control of the company passes to an Interim Resolution Professional (IRP).
Because admission triggers a moratorium and a change in management, a Section 7 case is high-stakes for both sides. The creditor needs airtight proof of default. The corporate debtor and its promoters need a fast, evidence-based response. Our IBC lawyers in Delhi act on both sides of this table.
⚠ Section 7 is not an ordinary recovery suit
Admission pauses litigation against the company and hands control to the IRP. It is meant to begin a collective resolution, not to chase a single debt. Before filing, we review whether the DRT, a commercial suit or negotiation would serve the lender better.
- Who files
- Financial creditor, singly or jointly
- Against
- Corporate debtor (company or LLP)
- Trigger
- Default in a financial debt
- Minimum default
- Rs 1 crore (Section 4 notification)
- Application
- Form 1, with evidence of default and IRP consent
- Forum
- NCLT bench with jurisdiction over the registered office
- Decision time
- 14 days to ascertain default (Section 7(4))
- If defects
- 7 days to rectify before rejection
- On admission
- Moratorium, public announcement, IRP, CoC
- Limitation
- 3 years from default, unless extended
- Appeal
- NCLAT in 30 days (+15), then Supreme Court
📌 Section 7 IBC at a glance
Who Can File a Section 7 Financial Creditor Petition?
A Section 7 application is open only to a financial creditor owed a financial debt. Getting this right at the start avoids a dismissal on maintainability.
Banks & Financial Institutions
Scheduled banks, public sector banks and financial institutions that have sanctioned and disbursed loans or credit facilities.
NBFCs & Asset Reconstruction Companies
NBFCs and ARCs holding loans or assigned debt. Assignees must show a valid assignment and a chain of title to the debt.
Home Buyers (Allottees)
Allottees of a real estate project are treated as financial creditors. A Section 7 application must be filed jointly by 100 allottees or 10 percent of allottees of the same project, whichever is less.
Lenders & Investors with Financial Debt
Any person to whom money is owed against the time value of money, including debentures, bonds and certain structured advances.
Joint Applicants
Financial creditors can file together as a group. Joint filing can help meet thresholds and share cost.
Guarantors Who Paid
A guarantor who has discharged the liability of a corporate debtor may acquire rights as a creditor, subject to the facts and documents.
📌 Who cannot file under Section 7
An operational creditor, such as a supplier owed for goods or services, uses Section 9 after a demand notice, not Section 7. Financial service providers such as certain NBFCs follow a separate regime where the application is initiated through the regulator. We check the debtor's status before filing.
Financial Debt, Default and the Rs 1 Crore Threshold
Financial debt under the IBC is a debt, including interest, disbursed against the consideration for the time value of money. It covers term loans, working capital, debentures, bonds, finance leases, guarantees and amounts raised from home buyers, among other categories.
Default means non-payment of a debt when the whole or any part or instalment has become due and payable and has not been paid by the debtor. A single missed instalment can qualify, provided the amount of default meets the Rs 1 crore minimum.
The creditor must show that the debt is due and payable. For loans, this is normally supported by a recall notice, the NPA classification or the lender's statement of account. For home buyers, it is the delayed possession or failure to deliver the unit under the buyer's agreement.
📌 Evidence of default - information utility first
Section 7(3) lets the creditor prove default through a record from an information utility or other evidence such as certified bank statements. Banks usually rely on both. Our team structures the evidence so that it stands up on admission.
Which Companies Can Be Proceeded Against?
A Section 7 application lies against a corporate debtor, meaning a company or a limited liability partnership that owes a debt to any person. Proprietorships and ordinary partnership firms fall outside this route.
- Registered office in Delhi: the NCLT in New Delhi has jurisdiction.
- Guarantee-backed debt: the corporate guarantor can itself be a corporate debtor. The creditor chooses against whom to proceed.
- Related-party lenders: related-party financial creditors cannot vote on the Committee of Creditors.
- Insolvency pending or past: a company already in CIRP or past moratorium needs a separate check.
Documents Required to File a Section 7 Petition in Delhi
Form 1 is filed under the Insolvency and Bankruptcy (Application to Adjudicating Authority) Rules, 2016. Incomplete filings are the commonest reason for delay. Here is what we assemble.
Applicant and Corporate Debtor Particulars
Name, address, authorisation of the signatory, incorporation details and registered office of the corporate debtor, with board resolution or power of attorney for the applicant.
Proposed Interim Resolution Professional
Name, registration number and address of the proposed IRP, with the IRP's written consent in the prescribed form.
Particulars of the Financial Debt
Amount claimed to be in default, date of default, financial debt details, security held and the nature of the debt.
Evidence of Default
Information utility record, certified statement of account under the Bankers' Books Evidence Act, or other proof of default.
Loan Agreement & Security Documents
Sanction letter, facility agreement, hypothecation and mortgage deeds, guarantees and amendments, where relevant.
Recall Notice & NPA Proof
Loan recall or demand notice, NPA classification date and correspondence acknowledging the liability. Written acknowledgements can also extend limitation.
- Affidavit and verification supporting the application, and proof of the prescribed filing fee.
- Chronology of events with annexure index so the bench can find proof of default quickly.
- Service on the corporate debtor and copy to the proposed IRP and the regulator where applicable.
Section 7 IBC Process and Timeline - Step by Step
From a defaulted loan to admission and CIRP, here is how our NCLT lawyers in Delhi carry a Section 7 matter.
Case Review & Limitation Check
We examine the debt, date of default, security, guarantees and acknowledgements, and check that the claim is within three years or properly extended.
Strategy: Section 7, DRT or Commercial Suit
We advise whether CIRP is the right tool or whether the DRT, SARFAESI or a commercial suit better fits the objective.
Recall Notice & Evidence Pack
We settle the recall notice, collect the information utility record and certified statements, and map every annexure to Form 1.
Select the IRP & Draft Form 1
We identify an eligible proposed IRP, secure written consent and draft Form 1 with the chronology and legal grounds.
Filing Before the NCLT
We file before the NCLT bench with jurisdiction over the registered office and serve the corporate debtor.
Admission Hearing
The NCLT ascertains default within 14 days of receipt. If there are defects, 7 days are given to rectify. We argue for admission, or for rejection when defending.
Moratorium, IRP & Public Announcement
On admission, the moratorium starts, the IRP takes control, a public announcement invites claims and the Committee of Creditors is formed.
CIRP, Resolution Plan or Liquidation
We represent the creditor or debtor through claims, CoC meetings and plan approval. The process ordinarily runs to 330 days including litigation time.
| Stage | Statutory reference | Time |
|---|---|---|
| Ascertain default and admit or reject | Section 7(4) and 7(5) | 14 days from receipt |
| Rectify defects after notice | Proviso to Section 7(5) | 7 days |
| Communicate order to creditor and debtor | Section 7(6) | 7 days from admission or rejection |
| CIRP period | Section 12 | 180 days, extendable by 90 days, with 330-day outer limit |
| Withdrawal after admission | Section 12A | With 90 percent CoC approval |
| Appeal to NCLAT | Section 61 | 30 days, plus up to 15 days |
| Appeal to Supreme Court | Section 62 | 45 days |
Section 7, Section 9 and Section 10 IBC Compared
Choosing the right section decides whether the application survives admission.
| Point | Section 7 | Section 9 | Section 10 |
|---|---|---|---|
| Applicant | Financial creditor | Operational creditor | Corporate debtor itself |
| Type of debt | Financial debt | Goods, services, employee dues | Any, debtor seeks insolvency |
| Prior notice | Recall notice usual, no statutory demand notice | Mandatory Section 8 demand notice, 10 days | Board and shareholder resolution |
| Minimum default | Rs 1 crore | Rs 1 crore | Rs 1 crore |
| Dispute as a defence | Generally not, focus is on default | Pre-existing dispute defeats the application | Not applicable |
| Typical user | Banks, NBFCs, lenders, home buyers | Vendors, suppliers, service providers | Company that cannot continue |
Related: Experienced NCLT lawyer in Delhi · Corporate lawyers for NCLT · Money recovery lawyer in Delhi
How to Defend a Section 7 Petition
If your company has received a Section 7 notice from the NCLT, the first hearing matters. Admission changes control of the company, so the reply and the preliminary objections must be prepared quickly and on evidence.
- No default: the debt was paid, was not due, or the amount in default is below Rs 1 crore.
- Limitation: the default is older than three years and no acknowledgement extends it.
- Not a financial creditor or financial debt: the applicant's claim does not fit the statutory definitions.
- Defective application: incomplete Form 1, missing IRP consent or missing proof of default.
- Settlement or payment: a settlement reached before admission, which can be placed before the bench or lead to withdrawal.
- Jurisdiction or maintainability: wrong bench, wrong debtor or a regime that excludes the application.
Mistakes That Sink Section 7 Applications
⚠ Filing without checking limitation
A time-barred claim is rejected however large the debt. We trace every acknowledgement, balance confirmation and part payment before filing.
⚠ Weak proof of default
Statements without certification, or unreconciled figures, invite an adjournment or rejection. Evidence should match the amount pleaded.
⚠ Ignoring the notice or the first date
A debtor who does not appear or reply can be admitted into CIRP quickly. Early legal advice preserves options such as settlement.
💡 Use funding where cost is the barrier
Where the claim is strong but the legal cost is the obstacle, non-recourse litigation funding may be an option. See LegalFund commercial litigation funding. Subject to eligibility.
Key Supreme Court Judgments on Section 7 IBC
These decisions shape how the NCLT hears a financial creditor petition. We apply them to each matter.
Innoventive Industries v. ICICI Bank
Early ruling that once default and a financial debt are shown, the adjudicating authority looks at default and not at whether the debtor is solvent.
Swiss Ribbons v. Union of India
Upheld the constitutional validity of the IBC and the distinction between financial and operational creditors.
Pioneer Urban Land v. Union of India
Confirmed that home buyers are financial creditors and can invoke Section 7.
B.K. Educational Services v. Parag Gupta
Held that the Limitation Act applies to IBC applications and that Article 137 gives three years from default.
Manish Kumar v. Union of India
Upheld the threshold of 100 allottees or 10 percent for home buyer applications under Section 7.
Vidarbha Industries Power v. Axis Bank
Examined whether admission is automatic once default is shown, and the limited discretion of the adjudicating authority.
What Happens After a Section 7 Petition Is Admitted
- Moratorium (Section 14): suits, recovery actions and enforcement against the corporate debtor are paused.
- Interim Resolution Professional: takes over management, controls the assets and runs the process.
- Public announcement (Section 15): creditors file claims with the IRP.
- Committee of Creditors: formed of financial creditors, who decide on the resolution plan.
- Resolution plan or liquidation: a plan approved by the CoC goes to the NCLT. Without one, the company goes into liquidation.
- Personal guarantors: the creditor can also proceed against guarantors under the personal insolvency provisions.
Settlement, Section 12A Withdrawal and NCLAT Appeals
Many Section 7 petitions end in settlement. Before admission, parties can seek withdrawal from the NCLT. After admission, Section 12A permits withdrawal with the approval of 90 percent of the Committee of Creditors. Our lawyers negotiate and document these settlements so they are enforceable and recorded properly.
An order admitting or rejecting a Section 7 petition can be challenged before the NCLAT in New Delhi under Section 61, generally within 30 days (extendable by up to 15 days), and then before the Supreme Court under Section 62 within 45 days. Early drafting of appeal grounds protects the timeline.
📌 Interim relief matters
Where admission is imminent or has just happened, a quick appeal and application for interim relief can protect the company's operations. Call us immediately: +91 9599801188.
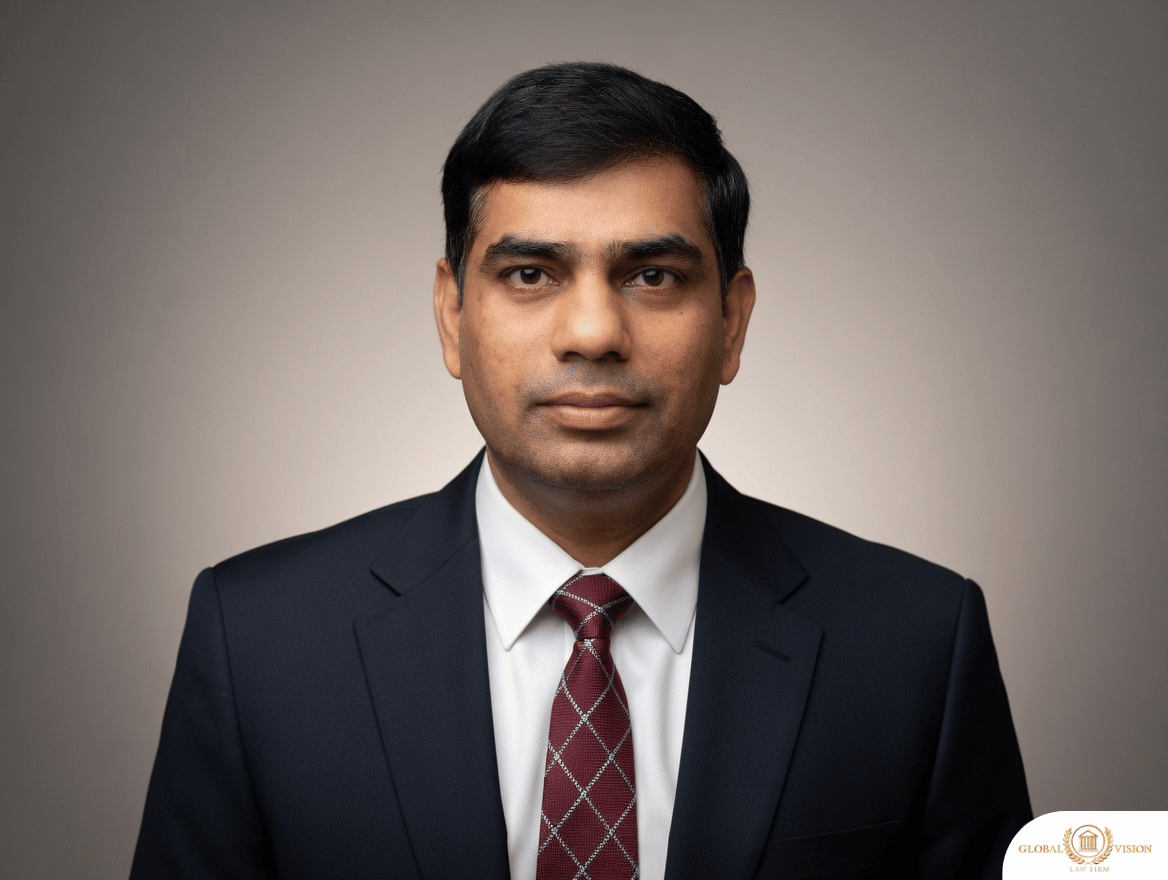
Meet Our IBC Section 7 Lawyer in Delhi - Adv. Amarendra Kumar Dubey
Founder & Managing Partner of Global Vision Law Firm - 13+ years of experience and 1400+ cases handled and successfully executed across Delhi's corporate and insolvency forums.
Adv. Rohan Malhotra
Associate Advocate with 6+ years specialising in Section 7 and 9 IBC applications, CIRP filings, and claims verification before the NCLT Delhi bench.

Adv. Niharika Verma
Associate Advocate with 6+ years in oppression and mismanagement matters, resolution plan review, and NCLAT appeals before Delhi's corporate law forums.
Why Delhi Businesses Choose Global Vision Law Firm for NCLT Matters
13+ years of experience and 1400+ cases handled and successfully executed across Delhi's corporate and insolvency forums.
Frequently Asked Questions - IBC Section 7 Financial Creditor Petition
Straight answers on filing, defending and appealing a Section 7 application in Delhi.
Section 7 of the Insolvency and Bankruptcy Code, 2016 allows a financial creditor, alone or jointly with other financial creditors, to apply to the NCLT to start the Corporate Insolvency Resolution Process (CIRP) against a corporate debtor once a default has occurred. It is filed in Form 1 along with proof of the financial debt and the default.
A financial creditor, such as a bank, NBFC, financial institution, lender or any person to whom a financial debt is owed, can file. Home buyers (allottees) of a real estate project are also treated as financial creditors, but a Section 7 application by allottees must be filed jointly by at least 100 allottees or 10 percent of the total allottees of the same project, whichever is less.
The minimum amount of default is Rs 1 crore, as notified by the Ministry of Corporate Affairs under Section 4 of the IBC in March 2020. Below this threshold, a Section 7 application cannot be filed.
Generally no. Unlike an operational creditor's Section 9 application, a Section 7 application does not fail merely because the debtor raises a dispute. The Adjudicating Authority looks at whether a financial debt exists and whether a default has occurred.
The Adjudicating Authority is required to ascertain the existence of default within 14 days of receiving the application, and to admit or reject it. In practice, listing and hearings can take longer. If the application is incomplete, the applicant is given 7 days to rectify the defects.
The CIRP commences on the date of admission. A moratorium under Section 14 takes effect, a public announcement is made, an Interim Resolution Professional takes over the management of the corporate debtor, and a Committee of Creditors is constituted.
The Limitation Act, 1963 applies to the IBC. The Supreme Court has held that Article 137 applies, giving three years from the date of default, subject to extension through a written acknowledgement of the debt under Section 18 of the Limitation Act.
The core documents are the loan or facility agreement, sanction letter, security documents and guarantees where relevant, statement of account, record of default from an information utility or other evidence, the recall or demand notice, the written consent of the proposed Interim Resolution Professional, and the Form 1 particulars.
Yes. Before admission, withdrawal can be sought from the Adjudicating Authority. After admission, withdrawal is possible under Section 12A with the approval of 90 percent of the voting share of the Committee of Creditors.
Appeals against an NCLT order lie to the NCLAT under Section 61 of the IBC, generally within 30 days, which the NCLAT can extend by up to 15 days. A further appeal on questions of law lies to the Supreme Court under Section 62, within 45 days.
Yes. A financial creditor can pursue the personal guarantor of a corporate debtor under the personal insolvency provisions of the IBC, and where CIRP of the corporate debtor is pending, the application is made before the same NCLT bench.
The NCLT bench having territorial jurisdiction over the registered office of the corporate debtor. For companies registered in Delhi, this is the NCLT in New Delhi. Appeals go to the NCLAT in New Delhi.
It depends on the objective. Section 7 starts a collective resolution process and not a simple recovery suit, so it suits cases where the corporate debtor is genuinely insolvent or a resolution is the aim. For straightforward recovery against secured assets, the DRT or a commercial suit may fit better. Each case needs a short strategy review.
Common defences include absence of default, debt not due, the claim being time-barred, the applicant not being a financial creditor, the debt not being a financial debt, defects in the application and settlement or payment before admission. A prompt, evidence-backed reply matters.
Global Vision Law Firm is led by Advocate Amarendra Kumar Dubey, with 13+ years of experience and 1400+ cases handled and successfully executed, including Section 7, 9 and 10 IBC applications, CIRP representation and NCLAT appeals.
This page is for general information on the Insolvency and Bankruptcy Code, 2016 and does not constitute legal advice. Thresholds, timelines and case law can change, and each matter turns on its own facts. Please consult an advocate before acting.
Need an IBC Section 7 Lawyer in Delhi?
Filing or defending a Section 7 financial creditor petition? Global Vision Law Firm - 13+ years, 1400+ cases handled and successfully executed. Free first consultation. Call now.